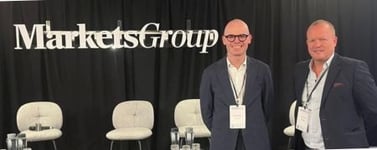
The sentiment across the European private equity market is materially more positive than it was twelve months ago, with market participants reporting that transaction activity, exits and fundraising conditions are improving. But as reflected at this year’s Markets Group Private Equity Europe Forum in London, recovery remains uneven.
Although capital remains available, it is increasingly concentrated around high-quality assets, experienced managers and sectors benefiting from long-term structural themes, against a persistent backdrop of geopolitical tension. In particular, there has been a notable shift in investment focus towards AI infrastructure, defence and resilience, and operationally resilient businesses.
Together, this is creating a new landscape for European private equity, where investors and managers are looking for attractive opportunities but at the same time need the support and expertise of service providers that have deep experience in governance, cross-border execution and operational scaling.
Understanding where the pockets of opportunity are, and how to leverage and scale those opportunities, is a critical issue for European managers.
Shift in momentum
Over the past few years, the industry has largely adopted a ‘wait and see’ approach, in the hope that rates would lower, exit markets would improve and values would see some sort of alignment. The consensus view now is that sponsors can no longer wait for market conditions to improve, and that value needs to be created instead through operational enhancements.
There are a number of repercussions arising from the shift in momentum, with buyers becoming increasingly selective. High-quality assets are benefiting from this and are proving attractive, while businesses with strong cashflows, defensible market positions and operational improvement are also attracting attention.
For fund managers, the focus has moved from needing vanilla administrative support to requiring providers that can add genuine value at a strategic level, through operational scaling and the seamless execution of institutional cross-border capital.
AI as infrastructure
AI, meanwhile, remains one of the most significant investment themes globally, with the conversation having now moved on from hype around application, and more towards the infrastructure required to support it.
Infrastructure assets including data centres, semiconductors, energy, fibre networks and cloud businesses are now key areas of focus among investors, but evidence of measurable value rather than just experimentation is the order of the day.
At a fund servicing level, this requires a far more sophisticated approach to analytics, while at a structuring perspective, it is prompting a rise in demand for AI-focused venture capital and digital infrastructure funds, as well as private credit strategies that can support AI infrastructure investment.
These are all sectors where Jersey structures, from investment funds to corporate and SPV vehicles, are increasingly relevant.
Defence becomes mainstream
It is perhaps no surprise against a backdrop of persistent geopolitical uncertainty that defence and national security continue to be key areas of focus for managers and investors.
Increased defence spending across Europe, persistent security concerns in relation to Ukraine, a greater focus on sovereign capability, and the protection of critical infrastructure have all played into this narrative, where the watchword is ‘resilience’.
This is creating opportunities in core and increasingly tech-driven areas such as defence technology, cyber security, AI-enabled military systems, and space and satellite infrastructure. Overall, it’s a sector that is no longer on the periphery but is now a mainstream private capital strategy.
Maximising the opportunity in this space, however, requires managers to have a knowledge of government-backed investment schemes and to be able to access suitable infrastructure and venture fund vehicles, backed up by appropriate levels of governance and oversight.
European appeal
Meanwhile, despite political uncertainty, through a geographical lens Europe remains attractive. There are sound structural reasons for this.
German infrastructure spending programmes and a strong industrial and engineering sector, for instance, are combining with an improving inflationary outlook and attractive valuations relative to the US to create a solid base.
As a result, managers are identifying better value opportunities in Europe compared to some parts of the US.
Liquidity and fundraising
Despite the well-founded positivity there are, of course, challenges.
Fundraising remains a particular challenge. Conditions are improving, but capital is concentrated around established managers with strong track records. This means that, while large managers can raise capital successfully, emerging managers continue to face longer fundraising cycles.
Linked to this, liquidity remains a structural issue too. Investors need to see distributions before making new commitments, but GPs need exits to demonstrate performance. It’s a ‘catch 22’ situation in a fundraising environment that is still protracted and slow.
There are some interesting consequences stemming from this challenge, though. In particular, options that were once considered ’emergency tools’ – continuation funds, GP-led secondaries, structured liquidity solutions – are now embedded as permanent components of the private markets ecosystem.
As the market continues to adapt to these challenges, the indications are that we will continue to see innovative and creative solutions like these come to the fore.
Evolution
The European private equity market is on a positive trajectory, continuing to evolve into a more specialised and operationally focused ecosystem where value creation, liquidity management, AI infrastructure, defence spending and resilience are becoming the dominant investment themes.
As managers look to seize these opportunities, navigate the challenges posed by liquidity and fundraising, and make the most of a more sophisticated structuring landscape, demonstrating operational excellence and institutional governance will be more important than ever.
Harnessing the right jurisdictional and service provider support, however, will help ensure they capture disproportionate amounts of capital over the coming years.
Speak to our experts today
Get in touch with our Funds team to find out how we can support you with your fund administration and governance needs.